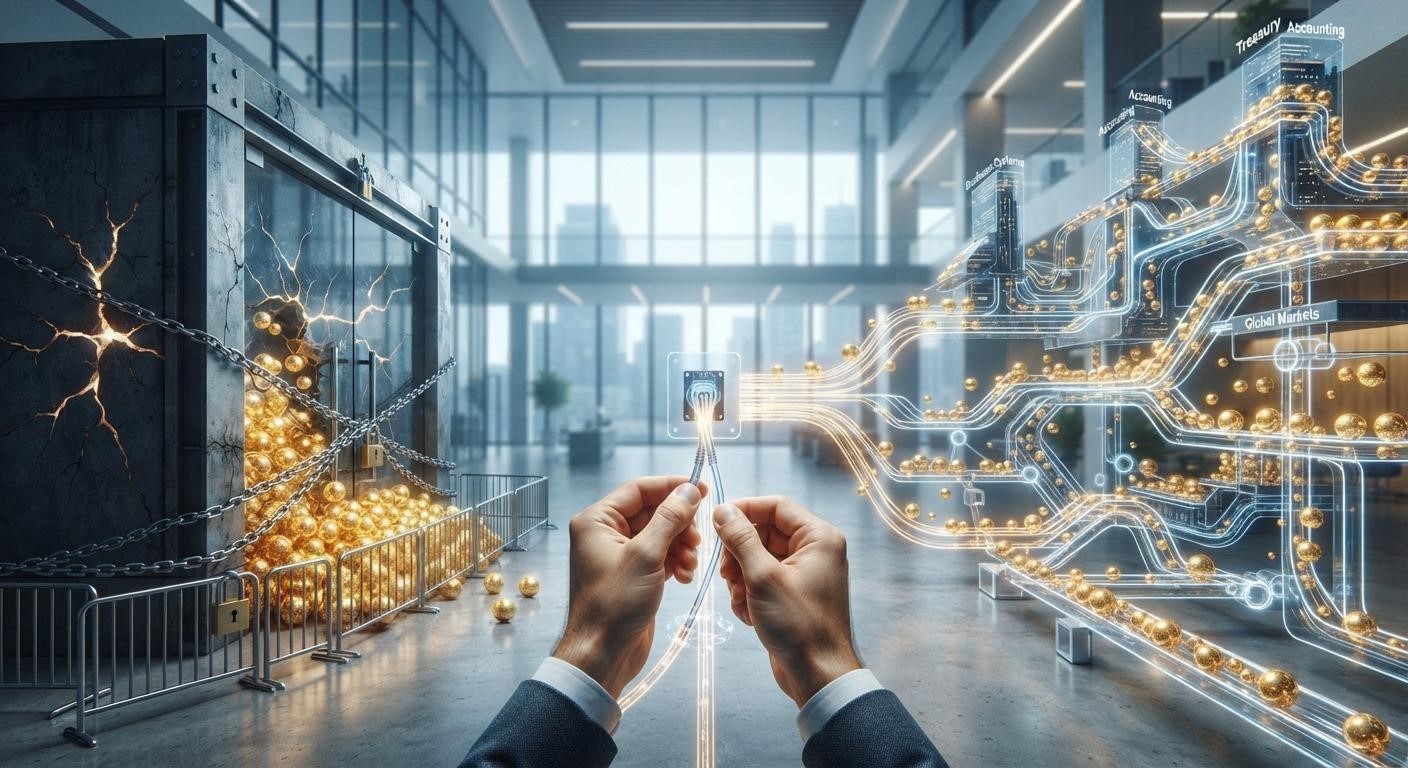
In an interconnected world where payment digitization is growing exponentially, companies face a key strategic decision: continue relying on closed solutions or adopt open infrastructures based on Application Programming Interfaces (APIs). For years, closed platforms offered convenience and rapid implementation, but at the cost of less flexibility, control, and innovation. Today, the landscape has evolved: payment APIs let organizations build tailored payment experiences, integrate with multiple providers, lower operating costs, and adapt to changing regulations and user behaviors. Below, we explain why this shift is occurring and what a company gains by adopting an API-based architecture.
The problem with closed solutions
A closed payment solution is one in which the provider controls all aspects of processing, from the user interface down to final settlement. The client accepts the conditions imposed, and any necessary adjustment—such as integrating a new payment method, modifying an approval workflow, or accessing real-time transactional data—depends entirely on the provider’s willingness and timeframe. This dependency is known as vendor lock-in, and its true cost becomes apparent when the enterprise needs to scale or migrate platforms.
As a business grows exponentially, several challenges can hinder payment execution. For example, a marketplace that starts by processing one hundred monthly payments may need to process ten thousand within a year; a closed platform lacking scalability forces the enterprise to migrate to another system at the worst possible time. Furthermore, the monolithic architecture of these solutions creates accumulated technical debt: each update requires provider intervention, each new requirement becomes a months-long project, and the company ends up paying for unused features while lacking the ones it genuinely needs.
Control with open APIs
A payment API is an interface that enables internal corporate systems to communicate directly with the provider’s infrastructure to initiate, authorize, and settle transactions without manual intervention. Unlike a closed solution where the provider dictates the workflow, an API returns control to the client, letting the company decide how payment integrates into its product, what data it receives at any moment, and which business rules apply to each transaction.
This flexibility translates into concrete operational advantages. A company can update its user experience without affecting the underlying processing system—for instance, integrating new payment methods in a few days rather than months, or configuring smart routing rules to direct each transaction to the most appropriate provider based on country, currency, or recipient profile.
Scalability for mass payments
Companies managing global payrolls or affiliate commissions need infrastructure that can process thousands of transactions in a single batch without degrading performance. An enterprise-grade payment API can process hundreds or thousands of disbursements in a single call, automatically managing queues, retries, and real-time status tracking. This capability distinguishes open infrastructures from closed solutions, which typically rely on scheduled processing cycles and human oversight for each batch. For an enterprise that selects a scalable platform as the foundation of its treasury, a payment API is not merely a technical add-on but the primary mechanism that guarantees timely execution—even during peak demand.
Integration with existing systems
A primary reason companies migrate to open infrastructure is the need to connect payments directly to existing systems: Enterprise Resource Planning (ERP), Customer Relationship Management (CRM), accounting software, and treasury management platforms. Closed solutions often force companies to adapt their internal workflows to the platform’s constraints, leading to duplicate records and reconciliation errors.
Modern APIs allow payment infrastructure to adapt to the enterprise’s existing systems instead. Through standardized endpoints, the accounting system can automatically transmit a payment order to the provider’s API, receive real-time confirmation, and log the transaction without human intervention. Additionally, utilizing payment APIs reduces initial development timelines, eliminates extra compliance audit prep work, and provides 100% transaction traceability. For an enterprise operating in a crypto payments ecosystem, a well-documented API can mean the difference between managing payments from an external dashboard and integrating them natively into daily operations.
Implementation speed and cost reduction
The time it takes an enterprise to integrate and launch a payment solution directly affects its operating costs. Closed solutions, characterized by prolonged setup processes and custom development, can consume weeks or months of technical effort before processing the first transaction.
Open APIs dramatically reduce time-to-market. A development team can integrate a full payment workflow within hours or days using clear documentation, sandbox environments, and production-ready SDKs. This speed reduces development costs and lets the business generate value immediately. When evaluating a B2B payment provider, review the quality of its technical documentation and confirm a sandbox environment is available to test the integration beforehand.
The future of corporate payments is open
The migration toward an open payment infrastructure is not a passing trend, but a structural response to the limitations of closed models. Companies operating globally need systems that scale with their growth, connect seamlessly with existing tools, and retain full control over financial operations without being tied to a third party’s roadmap. Open APIs embody this paradigm shift: rather than the enterprise adapting to the provider, the provider adapts to the enterprise.
What are your thoughts on this topic? Are you aware of other benefits payment APIs bring to businesses?
If you are interested in an enterprise payment API, you can contact us by visiting the following link.